Working as a locum doctor can give you more flexibility than a traditional salaried role, but the tax side can become complicated quickly.
Depending on how your arrangement is structured, you may need to deal with an ABN, GST, PAYG instalments, business deductions, superannuation and potentially the Personal Services Income (PSI) rules.
The first thing to understand is that having an ABN does not automatically make you an independent contractor. Some locum doctors are employees, while others operate as contractors. Your actual working arrangement determines the tax and super treatment.
This guide explains the main tax issues locum doctors in Australia need to understand for the 2026–27 financial year.
Are Locum Doctors Employees or Contractors?
This is the first question to answer before worrying about GST or company structures. A locum doctor may work through:
- a hospital
- a medical practice
- a locum agency
- another healthcare business
- their own business arrangements.
Some arrangements are employment arrangements where the hospital or practice pays you through payroll and withholds PAYG tax.
Others are contracting arrangements where you operate a business, invoice the client or agency and manage your own tax affairs.
Importantly, an ABN or invoice does not by itself determine whether you are a contractor.
The actual contractual and working relationship needs to be considered.
This distinction also matters for superannuation. In some circumstances, a contractor can still be treated as an employee for super guarantee purposes where the contract is principally for their personal labour and skills. The ATO specifically notes that having an ABN does not change that outcome.
Do Locum Doctors Need an ABN?
If you are genuinely carrying on an enterprise as a contractor, you may need an Australian Business Number (ABN).
An ABN allows you to identify your business when dealing with clients, agencies and the ATO, and it is normally used on invoices you issue.
But don’t make the mistake of thinking: “I have an ABN, therefore I am a contractor.”
The relationship comes first. The ABN comes second.
There is also a financial reason to get this right. If you are carrying on a business and don’t quote an ABN when required, the payer may need to withhold tax from your payment at the applicable no-ABN withholding rate.
For many locum doctors, the more important question is therefore not simply “Do I need an ABN?” but: “Am I genuinely operating as a business, or am I actually an employee?”
If you’re starting out, our guide to what it means to be a sole trader in Australia explains the structure and obligations in more detail.
How Is Locum Doctor Income Taxed?
If you operate as a sole trader, your net business income is included in your individual tax return and taxed at your personal marginal tax rates.
There is no special flat tax rate for locum doctors.
For 2026–27, Australian resident individual tax rates include a 37% marginal rate for taxable income between $135,001 and $190,000, with the 45% rate applying above $190,000.
Your actual tax bill will depend on your taxable income, not simply your gross locum billings.
For example, a doctor who invoices $200,000 may have substantial legitimate business expenses. Their taxable income is based on the income remaining after eligible deductions, together with any other income and applicable tax adjustments.
Medicare levy, HELP or other study-loan obligations, private health insurance and your wider tax position can also affect the final amount.
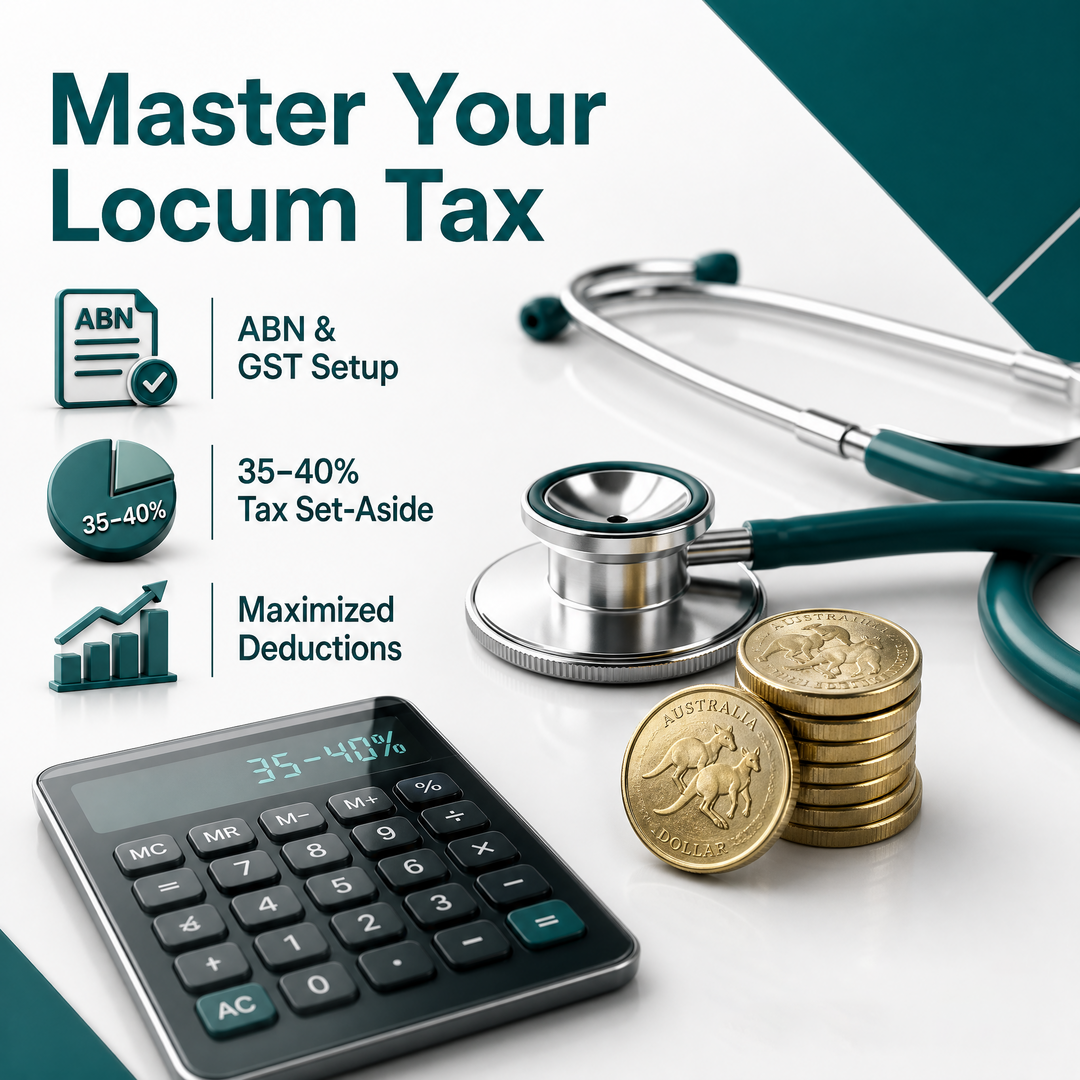
This is why simply putting aside “30%” or “40%” of every invoice is only a rough cash-flow strategy, not a calculation of what you actually owe.
Common Locum Doctor Tax Deductions
The good news is that locum doctors can have a range of legitimate business and work-related deductions where the relevant tax requirements are met.
Depending on your circumstances, these can include:
- AHPRA and professional registration fees
- professional indemnity insurance
- medical council or professional association fees
- eligible CPD and professional development costs
- medical equipment and specialist tools
- professional journals and subscriptions
- accounting and tax-agent fees
- business-use phone and internet expenses
- business software and technology
- eligible travel between work locations.
The key is that the expense needs to have the required connection with earning your assessable income, and private expenses generally need to be excluded or apportioned.
For a broader look at legitimate deductions and tax planning opportunities, see our guide on legal ways to reduce your tax bill.
GST for Locum Doctors: This Is Where It Gets Complicated
GST is one of the areas where locum doctors need to be particularly careful.
The GST registration threshold is generally $75,000 of GST turnover for businesses that are required to register.
But reaching the threshold does not mean every medical invoice should automatically have 10% GST added.
Why?
Because the GST treatment of health services depends on the nature of the supply and, importantly, who receives the supply.
The ATO explains that where a medical practitioner supplies services to another business, such as a medical clinic, that supply is generally not GST-free simply because the clinic subsequently provides a GST-free medical service to the patient. There are specific exceptions and third-party arrangements, so the contract and invoicing structure matter.
This means you should not rely on either of these assumptions: “I’m a doctor, so none of my services have GST.” or “I’m GST-registered, so I add 10% to everything I invoice.”
Neither is automatically correct.
The ATO’s GST and health guidance is worth reviewing, particularly where you work through a practice, hospital or agency.
For locum doctors with complex arrangements, it is often worth having the actual contract and invoicing process reviewed before you start charging GST.
PAYG Instalments: Tax You Pay During the Year
Contracting can create a cash-flow problem because you may receive your income without the same PAYG withholding that applies to an employee’s salary.
Once you are required to enter the PAYG instalment system, you make regular payments towards your expected income-tax liability during the year.
The ATO describes PAYG instalments as regular prepayments of expected tax on business and investment income, and instalments can generally be varied when your circumstances change.
The important thing for a new locum is to understand that your first tax return can create a double cash-flow effect:
You may have a tax bill for the year just completed while also starting instalments towards the next year’s tax.
That’s why maintaining a separate tax savings account is such a useful habit.
Rather than guessing a percentage forever, review your actual taxable income, deductions and PAYG position regularly.
Locum Travel and Vehicle Expenses
Travel can be one of the more valuable deduction areas for doctors working across multiple locations, but not every trip is deductible.
Travel between workplaces or work locations can potentially qualify where it has the necessary connection with earning your income.
Ordinary travel between your home and a regular workplace is generally private.
The distinction becomes particularly important for doctors working across several clinics or hospitals.
For the 2026–27 income year, the ATO’s cents-per-kilometre rate is 91 cents per kilometre, where that method is available and you meet the applicable requirements.
For more complex travel, particularly where you work across multiple locations or undertake interstate locum assignments, keep detailed records of the journey, destination, purpose and kilometres.
Don’t assume that calling yourself a “locum” makes every trip from home to a hospital tax deductible.
Accommodation and Interstate Locum Work
Interstate and regional locum work can raise additional questions around:
- flights
- accommodation
- vehicle hire
- meals
- travel between accommodation and workplaces
- temporary work locations.
Whether these costs are deductible depends heavily on the circumstances.
The distinction between travelling for work and effectively living somewhere to perform your work can be important, so large travel or accommodation claims should be reviewed rather than automatically treated as deductions.
Keep your contracts, booking records, invoices and evidence showing why the travel occurred.
Superannuation for Locum Doctors
Super is another area where locum doctors need to look beyond the label “contractor”.
If you are genuinely self-employed as a sole trader, you may need to make your own super contributions.
However, some contractors can still be treated as employees for super guarantee purposes where the contract is principally for their personal labour and skills.
That means having an ABN does not automatically mean you are responsible for your own super.
The actual contract needs to be considered.
For doctors who are genuinely self-employed, personal concessional super contributions may also provide a tax deduction, subject to the applicable contribution caps and eligibility requirements.
For 2026–27, the general concessional contribution cap is $30,000.
The right amount to contribute depends on your existing super balance, contribution history, cash flow, taxable income and other circumstances.
Sole Trader or Company: Which Is Better for a Locum Doctor?
This is where many high-income doctors receive overly simplistic advice.
You may hear: “You’re earning over $130,000. Set up a company.”
That’s not a sufficient reason.
A company can have genuine benefits, including legal separation and the ability to retain profits in the company where the circumstances allow.
But for a locum doctor, there is another major issue: Personal Services Income (PSI).
Personal Services Income: The Important Issue for Doctors
PSI is income that is mainly a reward for an individual’s personal efforts or skills.
That description can be highly relevant to medical professionals because the income may primarily arise from the doctor’s own professional labour.
The PSI rules can affect how income received through a company, trust or partnership is taxed and which deductions are available.
Agency arrangements can also affect the PSI analysis. The ATO specifically notes that obtaining work through an agency may prevent a business from passing some of the Personal Services Business tests.
That means setting up a company does not automatically turn a locum doctor’s personal professional income into freely distributable business profits.
Before incorporating, you should consider:
- whether the PSI rules apply
- how you obtain your contracts
- who the clients are
- whether you pass a Personal Services Business test
- how much income is being generated personally
- whether profits will actually be retained
- the additional company accounting and ASIC compliance costs
- asset protection and commercial risk.
Our sole trader vs company guide explains the broader structural differences, but locum doctors should get advice based specifically on their professional arrangements before incorporating.
BAS and GST Record-Keeping
If you are GST-registered, your BAS records need to accurately capture:
- GST collected
- GST credits on eligible purchases
- taxable and GST-free supplies
- PAYG instalments where applicable
- other relevant activity-statement obligations.
Most small businesses report quarterly, although the exact reporting cycle depends on your circumstances.
For 2026–27, the ATO has also applied a 5% GDP adjustment factor when calculating quarterly GST and PAYG instalment amounts for applicable taxpayers.
Good bookkeeping makes this dramatically easier.
Keep:
- invoices issued
- supplier invoices and receipts
- contracts with practices and agencies
- vehicle and travel records
- bank statements
- super contribution records
- professional registration and insurance documents.
Using cloud accounting software such as Xero or MYOB can make it much easier to keep everything reconciled throughout the year rather than reconstructing your records at tax time.
If you would rather have someone handle the quarterly compliance, our BAS lodgement service can manage your BAS and PAYG obligations for you.
The Biggest Tax Mistakes Locum Doctors Make
- Assuming an ABN makes them a contractor: It doesn’t. The actual working relationship matters.
- Adding GST to every invoice: The GST treatment depends on the supply and the recipient. Medical services and services supplied to practices can have different GST outcomes.
- Assuming a company automatically reduces tax: The PSI rules can be highly relevant to professional services income.
- Forgetting about super: A contractor may still be an employee for super guarantee purposes in certain labour-only arrangements.
- Treating every trip as a deduction: Travel from home to work is not automatically deductible because you work as a locum.
- Waiting until tax time: Locum income can be substantial and irregular. Waiting until the end of the financial year to discover your tax and PAYG position can create an unnecessary cash-flow problem.
Get Your Locum Tax Structure Right From the Start
Locum doctor tax is not simply a matter of registering an ABN and putting aside a percentage of every invoice.
Your tax position can involve contractor status, GST, PAYG instalments, deductions, superannuation, PSI and business structure — and these areas can interact.
A structure that works for one doctor may be completely unsuitable for another.
At KSH TAX, we work with healthcare professionals and businesses across Australia to help clients understand their tax obligations, structure their affairs properly and stay ahead of BAS and tax deadlines.
Thinking about starting locum work, changing your structure or reviewing your current tax setup? Book a free consultation or call us on 08 6285 8110.